FEMA & International Trade · Mumbai, for clients across India
FEMA & FDI Consultants in India
FEMA and FDI consultants for companies entering India or investing abroad: clear guidance on FDI, overseas investment, trade agreements and FEMA compliance.
A senior advisor replies within one business day.
Is this you?
Cross-border payments and investment, market entry, FTAs and origin.
“Foreign parent funding the Indian subsidiary, need the FEMA route, pricing and reporting position settled.”
- Led by
- IRS (Retd.) officers
- Trade facilitated
- ₹1,000+ Cr
- Litigation handled
- ₹100+ Cr
- Approvals secured
- 25+
What we do
Your FEMA file, the way we would keep it.
Three stages, fifteen pieces of work, the same advisors at every one. They kept files like this inside the government for decades. Now the file is yours. Open any line for the detail.
- FEMA 1999
- NDI Rules 2019
- OI Rules 2022
- RBI Master Directions
- CAROTAR 2020
Who leads this area
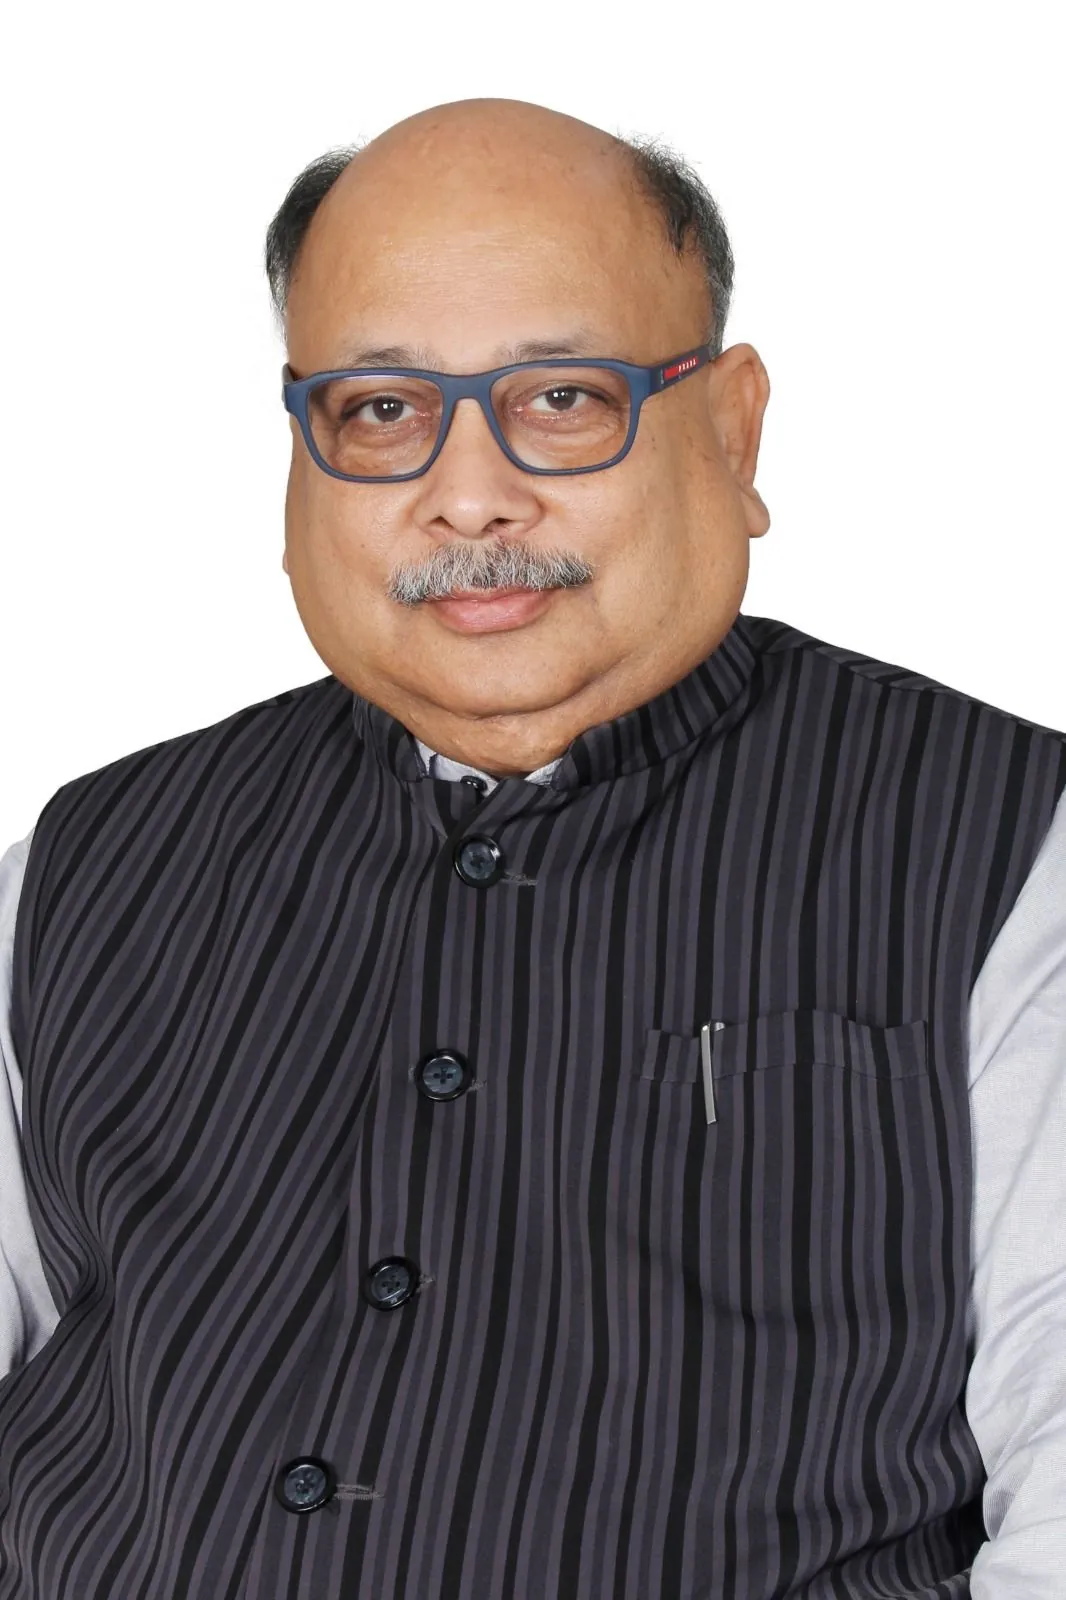
R. K. Jain, IRS (Retd.)
30+ years Indian Revenue Service · Customs, SEZ and Trade Policy
New to FEMA? The 60-second brief
Cross-border business in India is governed by three overlapping rulebooks: FEMA and the RBI's regulations on how money moves in and out; the entry-structure rules that decide whether you operate through a liaison office, a subsidiary, a zone or a distributor; and the trade agreements that decide the duty your goods pay. This desk sits at that intersection, one advisor across customs, GST, FEMA and FTP rather than four who do not talk to each other, for foreign investors entering India and Indian businesses building overseas.
TRADE BRIDGE ADVISORS LLP · MUMBAI
SUBJECT: FEMA
What has to be decided, applied for and signed before the first transaction.
Entry model: liaison / branch / project office, subsidiary, zone unit, direct sale
Liaison, branch, project office, subsidiary, FTWZ stock, GIFT City unit or direct import, each mapped for regulatory cost, tax footprint, permanent-establishment risk and time to first invoice.
FDI structuring and approvals
Sectoral caps and conditions under the Non-debt Instruments Rules, government-route applications where needed, downstream-investment rules and the pricing guidelines that govern the first share issue.
Overseas investment (ODI) by Indian companies
ODI under the 2022 Rules, the financial-commitment ceiling, the UIN, permitted structures and the annual reporting the investment carries for its life.
Non-resident banking (SNRR)
SNRR accounts and other rupee arrangements for non-residents with business in India, and the January 2025 changes that widened them (see our SNRR article in Insights).
FTA strategy at design stage
Which agreement your product qualifies under, the product-specific rule of origin, and how sourcing and processing should be arranged so the preferential rate is actually available, for exports and for imports.
The obligations, records and clocks that keep the benefit from leaking back as a demand.
Export realisation and EDPMS hygiene
Realisation within nine months, extensions and self write-off within the limits the Master Direction allows, and clearing EDPMS entries before they trigger caution-listing, which blocks the next shipping bill.
Import remittances and IDPMS
Six-month payment discipline, evidence-of-import submission, advance remittance rules and the closure of IDPMS entries against Bills of Entry.
FDI / ODI / ECB reporting: FC-GPR, FLA, APR
FC-GPR, FC-TRS, FLA, ODI APRs and ECB-2 filed on time, and Late Submission Fees or compounding avoided by calendaring rather than remembering.
FTA origin management: certificates of origin, CAROTAR records
Certificates of origin on DGFT's platform for exports; for imports, CAROTAR Form I knowledge, certificate validity, supplier declarations and the five-year record; handling an origin verification request without losing the preferential rate.
Transfer pricing meets customs value
Related-party pricing that satisfies both the income-tax transfer-pricing rules and Customs valuation and the SVB, because a year-end TP adjustment can become a customs demand.
Notices, exits, investigations and appeals, argued by people who sat on the deciding side of the desk.
Compounding with the RBI
Identifying the contravention precisely, regularising the underlying transaction first, and presenting the compounding application so it is compounded at the lower end of the framework rather than referred onward.
ED adjudication and appeals
Show-cause notices under s.16, the adjudication hearing, and appeals under ss.17 and 19, with the record built to show the transaction's genuineness and the absence of the elements that aggravate penalty.
Late Submission Fee and regularisation
Where a filing was merely late, using the LSF route rather than compounding, and getting FC-GPR, FLA, APR and ECB reporting back on the rails without a proceeding.
Caution-list removal
Clearing or extending the EDPMS bills that caused the listing and taking the exporter off the RBI's caution list so shipping bills stop being refused.
CAROTAR and origin disputes
Where a preferential rate is denied, the Customs demand is defended on the origin evidence and the procedure the officer followed under s.28DA, on the Customs ladder.
LICENCES OBTAINED HERE: BIS CRS REGISTRATION · BIS ISI CERTIFICATION · BIS ISI – FMCS (FOREIGN MANUFACTURERS) · BIS SCHEME X CERTIFICATION · BIS CERTIFICATION – FOOTWEAR · BIS CERTIFICATION – TOYS · BIS HALLMARKING – GOLD & SILVER · WPC–ETA APPROVAL · TEC CERTIFICATION · BEE REGISTRATION & STAR LABEL · FSSAI REGISTRATION & LICENCE · COSMETICS REGISTRATION (CDSCO) · MEDICAL DEVICE REGISTRATION (CDSCO) · EPR AUTHORISATION – E-WASTE · EPR REGISTRATION – PLASTIC PACKAGING · EPR REGISTRATION – BATTERY WASTE · EPR REGISTRATION – TYRES · EPR REGISTRATION – USED OIL · EPR – END-OF-LIFE VEHICLES · EPR ANNUAL RETURNS · MOEF&CC LICENCE · LMPC IMPORTER REGISTRATION · LMPC MODEL APPROVAL · LABELS & ARTWORK COMPLIANCE · SECTION 19 REGISTRATION · LM DEALER LICENCE
Our analysis on FEMA & International Trade.
All articles →
ON FILE: 5 ANSWERS, READY BEFORE YOU ASKThe FEMA situations we see most, and how we would handle each.
Open the file ▾Close ▴
Our foreign parent is funding the Indian subsidiary. What exactly do you deliver?
The FEMA route for the chosen instrument, the pricing-guideline position, the FC-GPR reporting inside its thirty-day window, and documentation the bank's compliance desk accepts the first time. Where the structure itself is still open, we start one step earlier: entry model, subsidiary, branch, project office or zone unit, chosen against your sector's FDI route and the five-year repatriation plan.
We have unrealised export invoices flagged in EDPMS. Can you clean it up?
Yes. Shipment-wise reconciliation first, then extension, set-off or write-off through your authorised dealer within its delegated powers, and the RBI where the case exceeds them. EDPMS hygiene is standing work on this page because a flagged exporter eventually becomes a caution-listed one, and caution-list removal is slower work than prevention.
We missed FEMA reporting for several years. What is the way back, and do you run it?
Regularisation is a lane, not a scandal, and we run it end to end: the Late Submission Fee where the delay qualifies, compounding with the RBI where it does not. We assemble the history, compute the exposure honestly, and take the application through. A record corrected voluntarily reads very differently from one discovered in your next transaction's due diligence.
Can you structure our overseas investment and keep it compliant?
Both halves: the design against the Overseas Investment Rules, 2022, Form FC through your bank before a rupee moves, and then the Annual Performance Reports for as long as the investment lives. Structures where money returns to India as FDI sit in a specifically regulated lane, and we design for that lane rather than discovering it later.
Customs is questioning our FTA origin claims under CAROTAR. Whose problem is that?
Legally yours, because Section 28DA puts the origin file on the importer, not the supplier. Our work is building that file, certificates, supplier declarations, cost data, running the verification response, and defending the differential-duty demand where the claim is sound. FTA strategy at design stage is the first line of this page's work precisely so this question never arrives.
YOUR SITUATION IS NOT ON FILE? TWO LINES ARE ENOUGH.
Ask your own question →Start here
Two lines are enough to start.
Tell us what is happening and attach the notice or approval if there is one. A senior advisor replies within one business day. Scope and fees are agreed in writing before work starts: annual retainership · project-based mandates · one-time representations & opinions.