Disputes & Representation · Mumbai, for clients across India
Customs & GST Show Cause Notice Reply Advisors in India
Show cause notice replies and appeals in customs and GST, across India: a robust defence, and representation before the authorities and the tribunals.
A senior advisor replies within one business day.
Is this you?
Notices, investigations, appeals in every regime; representations before Ministries and CBIC.
“Show-cause notice under the Customs Act, personal hearing in three weeks, need representation.”
- Led by
- IRS (Retd.) officers
- Trade facilitated
- ₹1,000+ Cr
- Litigation handled
- ₹100+ Cr
- Approvals secured
- 25+
What we do
Your Disputes file, the way we would keep it.
Fifteen pieces of work, filed by where your matter stands, from the first summons to the tribunal. They kept files like this inside the government for decades. Now the file is yours. Open any line for the detail.
- Customs Act ss.28, 108–110A, 124, 128–130E
- CGST ss.67–74A, 107–118
- FT(D&R) ss.11–16
- SEZ Rules r.55
- FEMA ss.13–19
Who leads this area
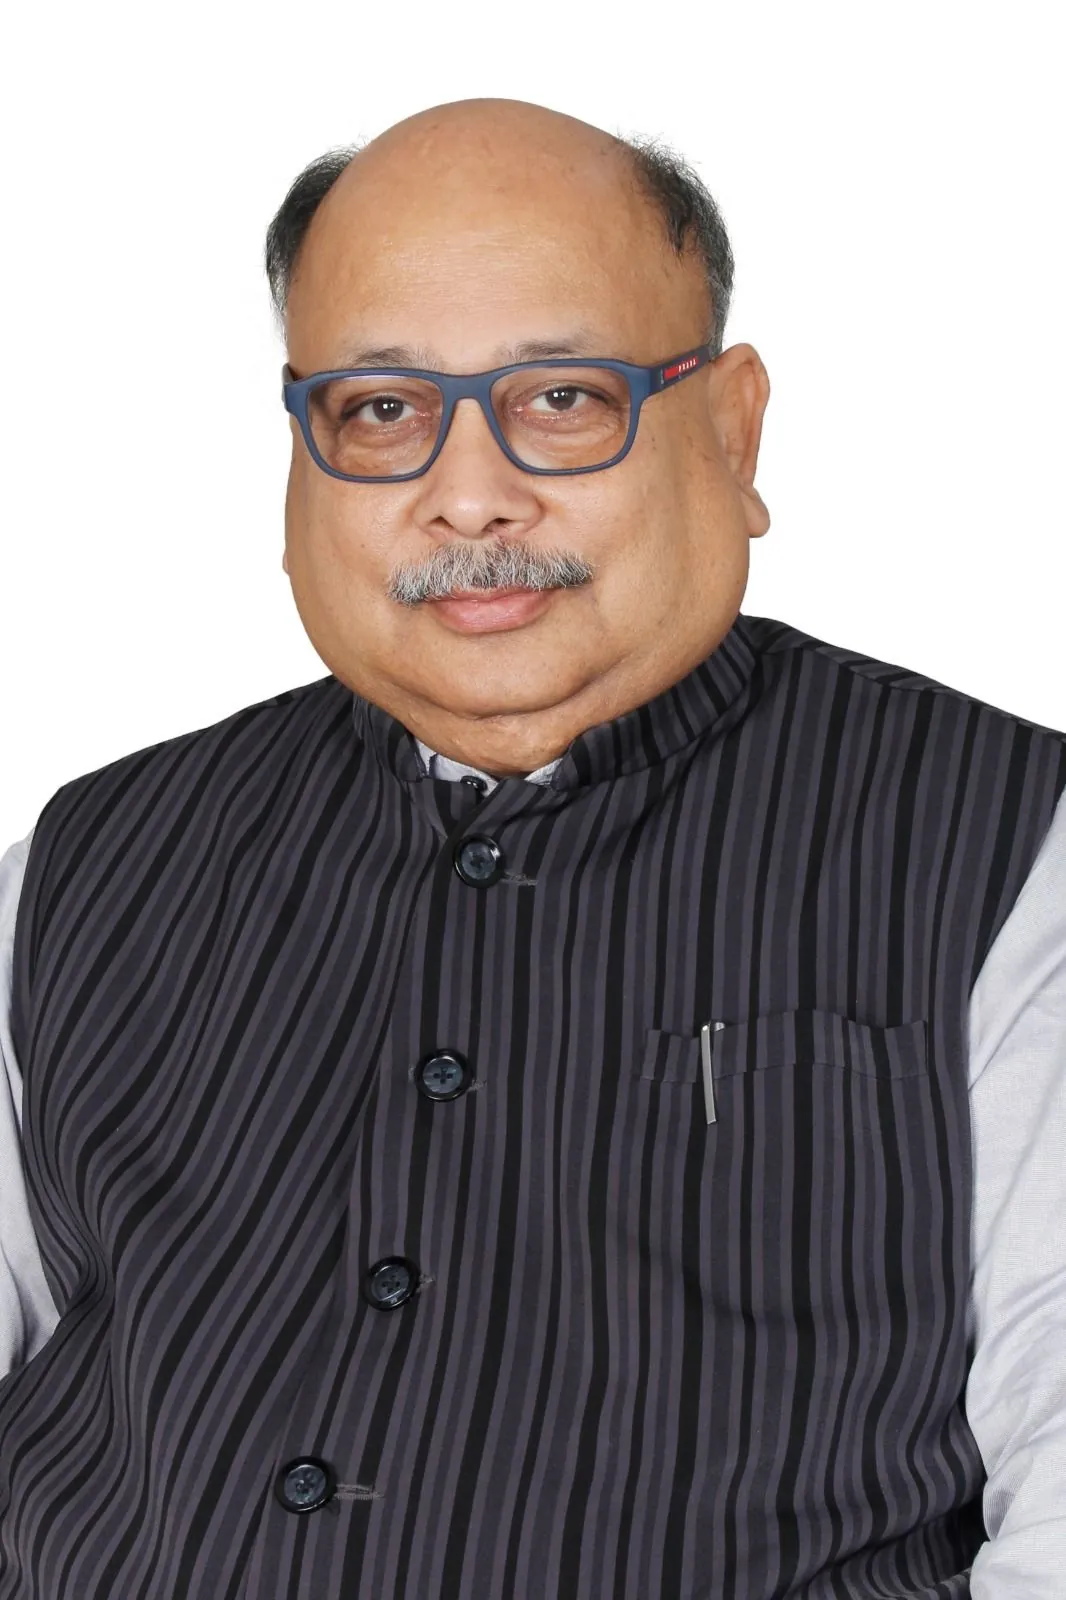
R. K. Jain, IRS (Retd.)
30+ years Indian Revenue Service · Customs, SEZ and Trade Policy
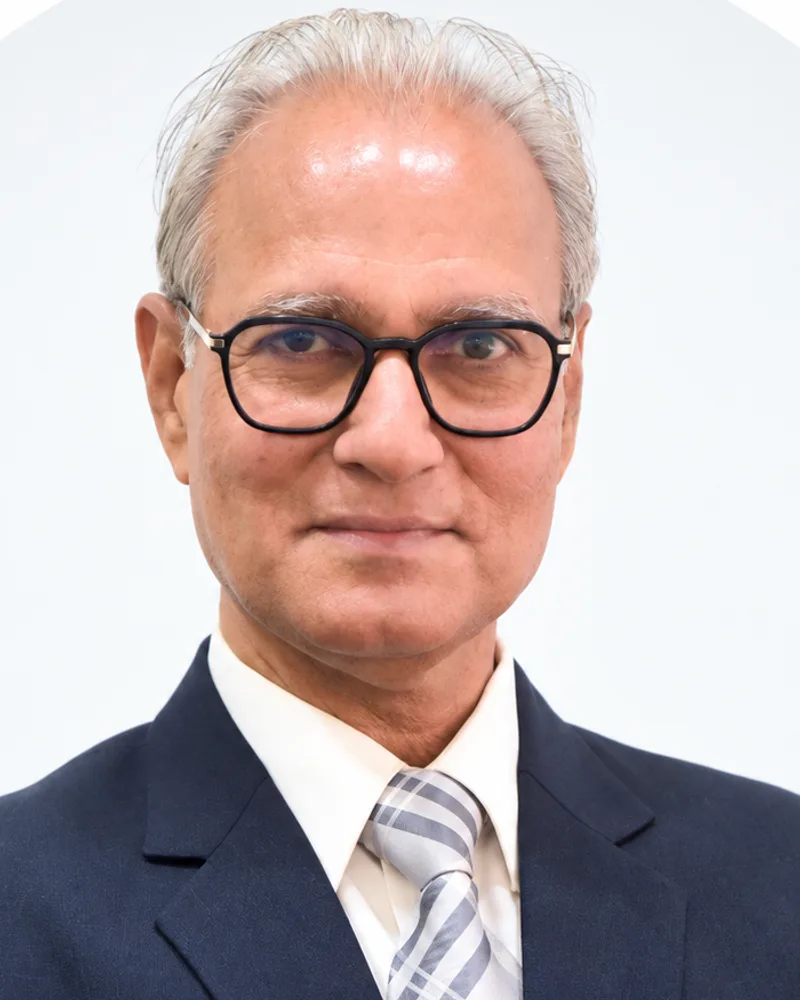
Subhash C. Varshney, IRS (Retd.)
35+ years Indian Revenue Service · Customs, Excise, Service Tax and GST
Ajit U. Nair, IRS (Retd.)
37+ years Mumbai Customs (CBIC) · Customs, Shipping and Trade Disputes
New to Disputes? The 60-second brief
Every trade regime ends in the same place when it goes wrong: a notice, a hearing and an appeal ladder, under the Customs Act, the CGST Act, the Foreign Trade (Development & Regulation) Act, the SEZ Rules, the IFSCA Act or FEMA. Outcomes turn on how the argument lands with the officer deciding it. Our senior advisors spent their careers as that officer, administering Customs and indirect tax before advising on it. Engage us directly when the notice has already arrived.
TRADE BRIDGE ADVISORS LLP · MUMBAI
SUBJECT: DISPUTES
Summons, statements and seizures, and the enquiry that decides what the notice will say.
Summons and statements
Preparation before the appearance, the record made during it, and the position on retraction, because a statement given badly on day one is the department's best exhibit in the notice.
Search, seizure and provisional release
The seizure memo, the panchnama, the s.110(2) clock, and a provisional-release application under s.110A on bond and security so goods and business move while the investigation runs.
The investigation-to-notice transition
Written submissions during the investigation that shape or pre-empt the show-cause notice, the stage most companies leave to silence.
Arrest, bail and prosecution exposure
The thresholds and procedure under Customs s.104 and CGST s.69, bail strategy with counsel, and compounding of offences under Customs s.137(3) and CGST s.138 where it is the right outcome.
FEMA and ED proceedings
ED show-cause and adjudication under FEMA, compounding with the RBI where the contravention qualifies, and appeals to the Special Director (Appeals) and the Appellate Tribunal.
The exposure, the forum and the reply that frames every later stage, with goods kept moving meanwhile.
Exposure assessment in the first thirty days
Duty or tax, interest and penalty computed on the department's theory and on yours; the limitation position stated plainly; the reduced-penalty and settlement options priced, so the decision to contest or to pay is made on numbers.
Forum and framing
Adjudication reply, committee representation, provisional release application, writ, or advance ruling, chosen for where the question is best decided, not by default.
The reply architecture: RUDs, hearing submissions
Relied-upon documents demanded and read; the extended-period allegation met on the department's own data; the merits argued from statute, notification and case law; the quantification re-done line by line.
Interim protection: provisional release, writs
Provisional release of seized goods under Customs s.110A, provisional assessment, stay applications and, where a proceeding is without jurisdiction, a writ petition, so operations continue while the dispute runs.
The hearing, the appeal ladder and the pre-deposits, argued on a record built for it.
Adjudication and the personal hearing
Written submissions, the hearing under Customs s.122A or GST s.75, the additional submissions the hearing generates, and the record that makes the order appealable if it goes wrong.
First appeals (CA-1 / APL-01)
Commissioner (Appeals) and the GST Appellate Authority, the grounds, the pre-deposit computed and paid correctly, condonation applications where a date has slipped, and the stay of recovery that follows.
Tribunals: CESTAT, GSTAT, and the courts
CESTAT and the GST Appellate Tribunal, appeal memoranda, the additional pre-deposit, cross-objections and the hearing, with counsel where the matter warrants it.
Refunds of pre-deposit and interest
Pre-deposits recovered with interest under Customs s.129EE and GST s.115 when the appeal succeeds, a step routinely forgotten after the order arrives.
Policy representations before Ministries, CBIC and DGFT, for one company or a whole trade body.
Committee and policy representations (Ministries, CBIC, DGFT)
UAC and BoA proposals and appeals, Norms and EPCG Committee applications, Policy Relaxation Committee relaxations and IMWG (SCOMET) applications, prepared for the way each Committee reads a file.
Policy advocacy for companies and trade bodies
Reasoned representations to the Ministries of Commerce and Finance, the Board of Trade and CBIC on behalf of industry bodies, the amendment drafted, not just the grievance stated.
LICENCES OBTAINED HERE: LM NOTICES & CASES
Our analysis on Disputes & Representation.
All articles →
ON FILE: 6 ANSWERS, READY BEFORE YOU ASKThe Disputes situations we see most, and how we would handle each.
Open the file ▾Close ▴
We have a show cause notice and a personal hearing in three weeks. Can you take it from here?
Yes, and the first deliverable arrives fast: an exposure assessment, duty, penalty, personal exposure, limitation, so you know what is actually at stake. Then the reply architecture: the relied-upon documents examined line by line, grounds framed, hearing submissions prepared, and appearance at the hearing. The reply is the case; everything that follows runs on the record it builds.
We are at the investigation stage: summons, statements, possibly a search. What is your role?
Preparation and presence. The person summoned under Section 108 or Section 70 goes in prepared, documents organised and the statement strategy settled; anything seized is pursued for provisional release; and the investigation-to-notice transition is watched so that nothing hardens into the record by default. The hour before the first appearance is the highest-value hour in the whole matter.
Our matter is already running with another consultant. Can you take it over mid-way?
Yes, and it happens most often exactly when a matter turns serious: after an unsatisfying reply, before a hearing, or with an appeal deadline approaching. We review the record as it stands, tell you honestly which earlier positions help and which hurt, and carry the matter forward from there. The record cannot be rewritten, but the strategy can.
If adjudication goes against us, do you run the appeals?
Through every rung this page lists: Commissioner (Appeals), CESTAT and GSTAT, and with counsel, the High Court. Pre-deposits are computed exactly, the stay on recovering the balance is put to work, and when a stage is won, the refund of pre-deposit with interest is pursued rather than forgotten, which happens more often than clients expect.
Our issue is with a Ministry or a policy body, not a tax officer. Do you do representations?
It is a named line of this page's work: representations before the Ministries, CBIC and DGFT, and policy advocacy for individual companies and trade bodies. Knowing which desk can lawfully grant what you need is half the representation, and careers spent inside those Ministries are the reason clients hand us this work.
Is there personal risk for our directors, and do you cover that as well?
We treat it as part of the same brief, because the department does: personal penalty notices under the Customs and GST provisions answered consistently with the company's record, arrest and bail exposure assessed honestly where investigation provisions reach individuals, and one coherent record kept across the company's file and every personal one.
YOUR SITUATION IS NOT ON FILE? TWO LINES ARE ENOUGH.
Ask your own question →Start here
Two lines are enough to start.
Tell us what is happening and attach the notice or approval if there is one. A senior advisor replies within one business day. Scope and fees are agreed in writing before work starts: annual retainership · project-based mandates · one-time representations & opinions.