GST · Mumbai, for clients across India
GST Consultants in India
GST consultants for importers, exporters and zone units across India: credits and refunds on imports, exports and zone supplies protected, processed and defended.
A senior advisor replies within one business day.
Is this you?
GST on the trade flow, imports, exports, SEZ/EOU supplies, refunds, notices.
“GST refund on exports stuck for two quarters, need the deficiency memo answered and the refund released.”
- Led by
- IRS (Retd.) officers
- Trade facilitated
- ₹1,000+ Cr
- Litigation handled
- ₹100+ Cr
- Approvals secured
- 25+
What we do
Your GST file, the way we would keep it.
Three stages, fifteen pieces of work, the same advisors at every one. They kept files like this inside the government for decades. Now the file is yours. Open any line for the detail.
- CGST / IGST Acts 2017
- CGST Rules rr.89–96B
- Schedule III
Who leads this area
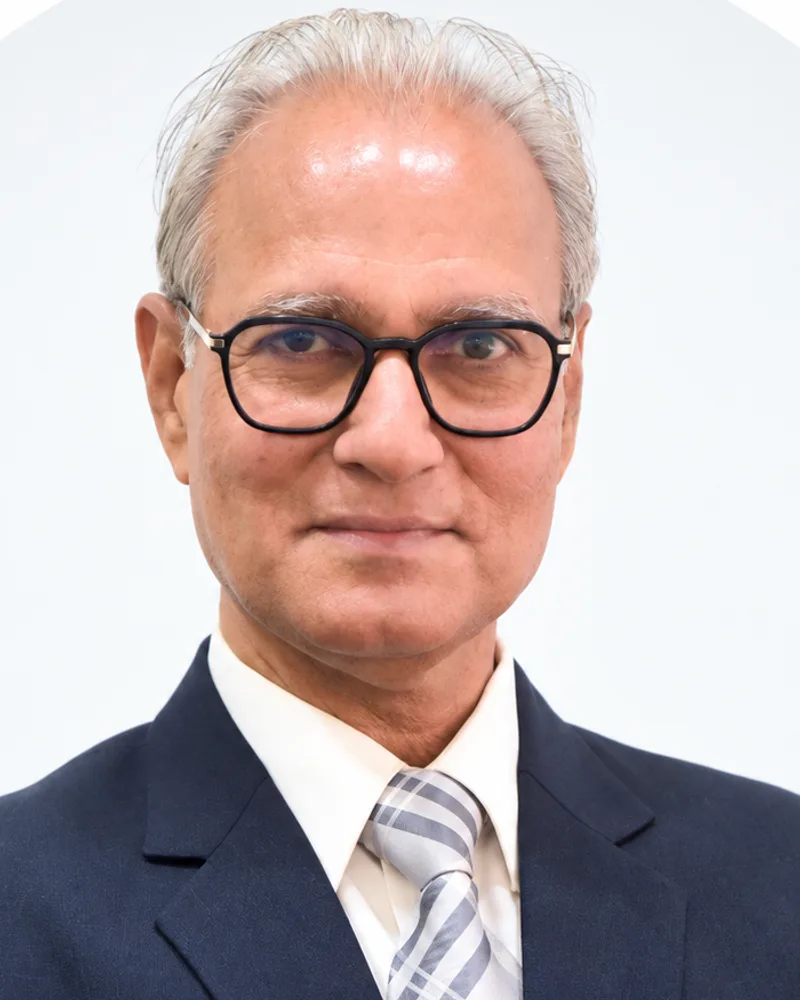
Subhash C. Varshney, IRS (Retd.)
35+ years Indian Revenue Service · Customs, Excise, Service Tax and GST
New to GST? The 60-second brief
For importers, exporters and zone units, GST concentrates at a few pressure points: whether a supply is zero-rated, whether a refund is filed right and followed through, whether the credit on imports and inputs survives audit, and how a transaction that also touches Customs, the FTP or the SEZ Rules is taxed. This desk handles the trade-facing side of GST, the part that lives at the intersection with customs, incentive schemes and zone operations, from advisors who administered indirect tax before GST existed and have watched every refund and notice pattern since.
TRADE BRIDGE ADVISORS LLP · MUMBAI
SUBJECT: GST
What has to be decided, applied for and signed before the first transaction.
Zero-rating done deliberately (LUT in RFD-11)
LUT under rule 96A or export with payment and refund under rule 96, chosen on your credit position and cash cycle; SEZ supplies with the Specified Officer's endorsement your refund will later need.
Place of supply for cross-border services
The s.13 default and its exceptions, the intermediary question, and how the contract is written so the export-of-services conditions in s.2(6) are actually met, payment in convertible currency, distinct persons and all.
Import IGST and credit
IGST at the port under s.3(7) of the Customs Tariff Act, credit through the bill of entry data in GSTR-2B, and the reverse-charge position on imported services under s.5(3) of the IGST Act.
Schedule III transactions: high-seas, in-bond sales
Merchant trade, high-sea sales and sales of goods in a customs bonded warehouse before clearance for home consumption, structured so the documents evidence the transaction the Schedule describes.
SEZ, EOU and deemed-export supplies
The GST treatment of SEZ, FTWZ and EOU procurement, DTA sales by zone units, deemed exports to EOUs and Advance Authorisation holders, and job-work movements, where GST, Customs and the SEZ Rules meet.
The obligations, records and clocks that keep the benefit from leaking back as a demand.
Refunds pursued to credit, not just to filing (RFD-01, deficiency memos)
RFD-01 prepared to the rule 89(4) formula with the turnover and net-ITC positions the officer will test; deficiency memos in RFD-03 answered without restarting the clock avoidably; provisional refund and s.56 interest claimed where due.
Shipping-bill refunds that actually flow (GSTR-1 ↔ ICEGATE)
The ICEGATE–GSTN matching that stalls rule 96 refunds, invoice and port-code mismatches, GSTR-1 table 6A errors, EGM gaps, found and cured, and rule 96B realisation tracked against EDPMS.
Credit protection: s.16(4) time limits, s.17(5) blocks
ITC eligibility and GSTR-2B reconciliation, blocked credits under s.17(5), the s.16(4) time limit and the relaxations in s.16(5)–(6), and the import-IGST credit trail from bill of entry to return.
SEZ, EOU and deemed-export refunds
Refunds by the DTA supplier or the recipient on deemed-export supplies under Notification 48/2017-CT, and the endorsement and declaration set each requires.
Returns, e-invoicing and s.65 audits by design
GSTR-1 export and SEZ tables, e-invoice fields that carry through to the shipping bill, and records built for the s.65 audit rather than reconstructed for it.
Notices, exits, investigations and appeals, argued by people who sat on the deciding side of the desk.
Pre-notice (DRC-01A) and the first reply
DRC-01A intimation answered so the notice never issues, or narrowed before it does; the s.73 / 74 / 74A reply built on limitation, on the merits and on quantification together.
Audits, DGGI and summons
s.65 audit findings answered before they harden into a notice; s.70 summons, statements and the DGGI investigation record handled from the first appearance.
Refund rejections and credit reversals
RFD-06 rejections and ITC-reversal demands appealed under s.107 on the specific ground the officer took, usually a formula, an endorsement or a time-limit point that has a statutory answer.
Detention of goods in transit (s.129)
s.129 detentions of export or zone-bound cargo, the notice, the seven-day clocks and the choice between paying under protest and contesting, made with the shipment's deadline in view.
Appeals and the pre-deposit ladder (ss.107, 112)
APL-01 to the Appellate Authority within three months; APL-05 to the GST Appellate Tribunal; the ten-per-cent deposits and their caps computed correctly, and refunded with interest when you win.
LICENCES OBTAINED HERE: GST REGISTRATION & AMENDMENTS
ON FILE: 6 ANSWERS, READY BEFORE YOU ASKThe GST situations we see most, and how we would handle each.
Open the file ▾Close ▴
Our GST refund on exports has been stuck for two quarters. What will you actually do?
We start at the record, not at the portal: shipping-bill refunds are reconciled between GSTR-1 and ICEGATE, LUT refunds are traced through the RFD-01 trail and its deficiency memos, and we find the exact point where your claim broke. Then the memo is answered the way the sanctioning officer's checklist reads, and the file is followed with the jurisdiction until it moves. This page lists the work as refunds pursued to credit, and that is the standard we run it to.
Can you set up our exports so refunds stop getting stuck?
That is the set-up work on this page: zero-rating done deliberately. The LUT kept current in RFD-11, invoice and shipping-bill data aligned before goods move, place-of-supply positions for cross-border services written down once, and SEZ and deemed-export supplies papered with the endorsements the refund will later depend on. One design exercise replaces quarters of chasing.
A DRC-01A intimation has arrived. Is that already a notice, and what do you do with it?
It is the pre-notice stage, and the cheapest place a GST dispute will ever be. We treat the intimation as the department showing its case early: we test the arithmetic and the legal position, reply where it is wrong, and advise paying where it is right, before it becomes a Section 73 or 74 notice with penalty attached. Advisors who spent careers on the deciding side of these files draft that reply.
A departmental audit or DGGI enquiry has started. What is your role while it runs?
Presence and record discipline: the documents the audit memo asks for are compiled and vetted before they go, replies to observations are drafted while they are still observations, and if the enquiry escalates into summons or a notice, nothing handed over earlier surprises us. Matters are lost in the gap between what was given to the department and what the reply later claims; we keep the two identical.
Our input credit is being questioned under s.16(4) and s.17(5). Can you defend it?
Yes, and in both directions. We audit the credit ledger against the time limits and the blocked categories, defend what is defensible in the reply and the hearing, and just as importantly re-engineer the procurement and documentation flows that keep producing the same exposure, so the next audit finds less to question.
Our goods were detained in transit under s.129. How do you handle it?
Release first, argument second. Section 129 lets the goods move on payment or security, so we prepare the security and the reply immediately and get the vehicle back on the road; the penalty question is then fought on the merits without demurrage running against you. Detention work is listed on this page as its own line because speed of sequence is the whole job.
YOUR SITUATION IS NOT ON FILE? TWO LINES ARE ENOUGH.
Ask your own question →Start here
Two lines are enough to start.
Tell us what is happening and attach the notice or approval if there is one. A senior advisor replies within one business day. Scope and fees are agreed in writing before work starts: annual retainership · project-based mandates · one-time representations & opinions.